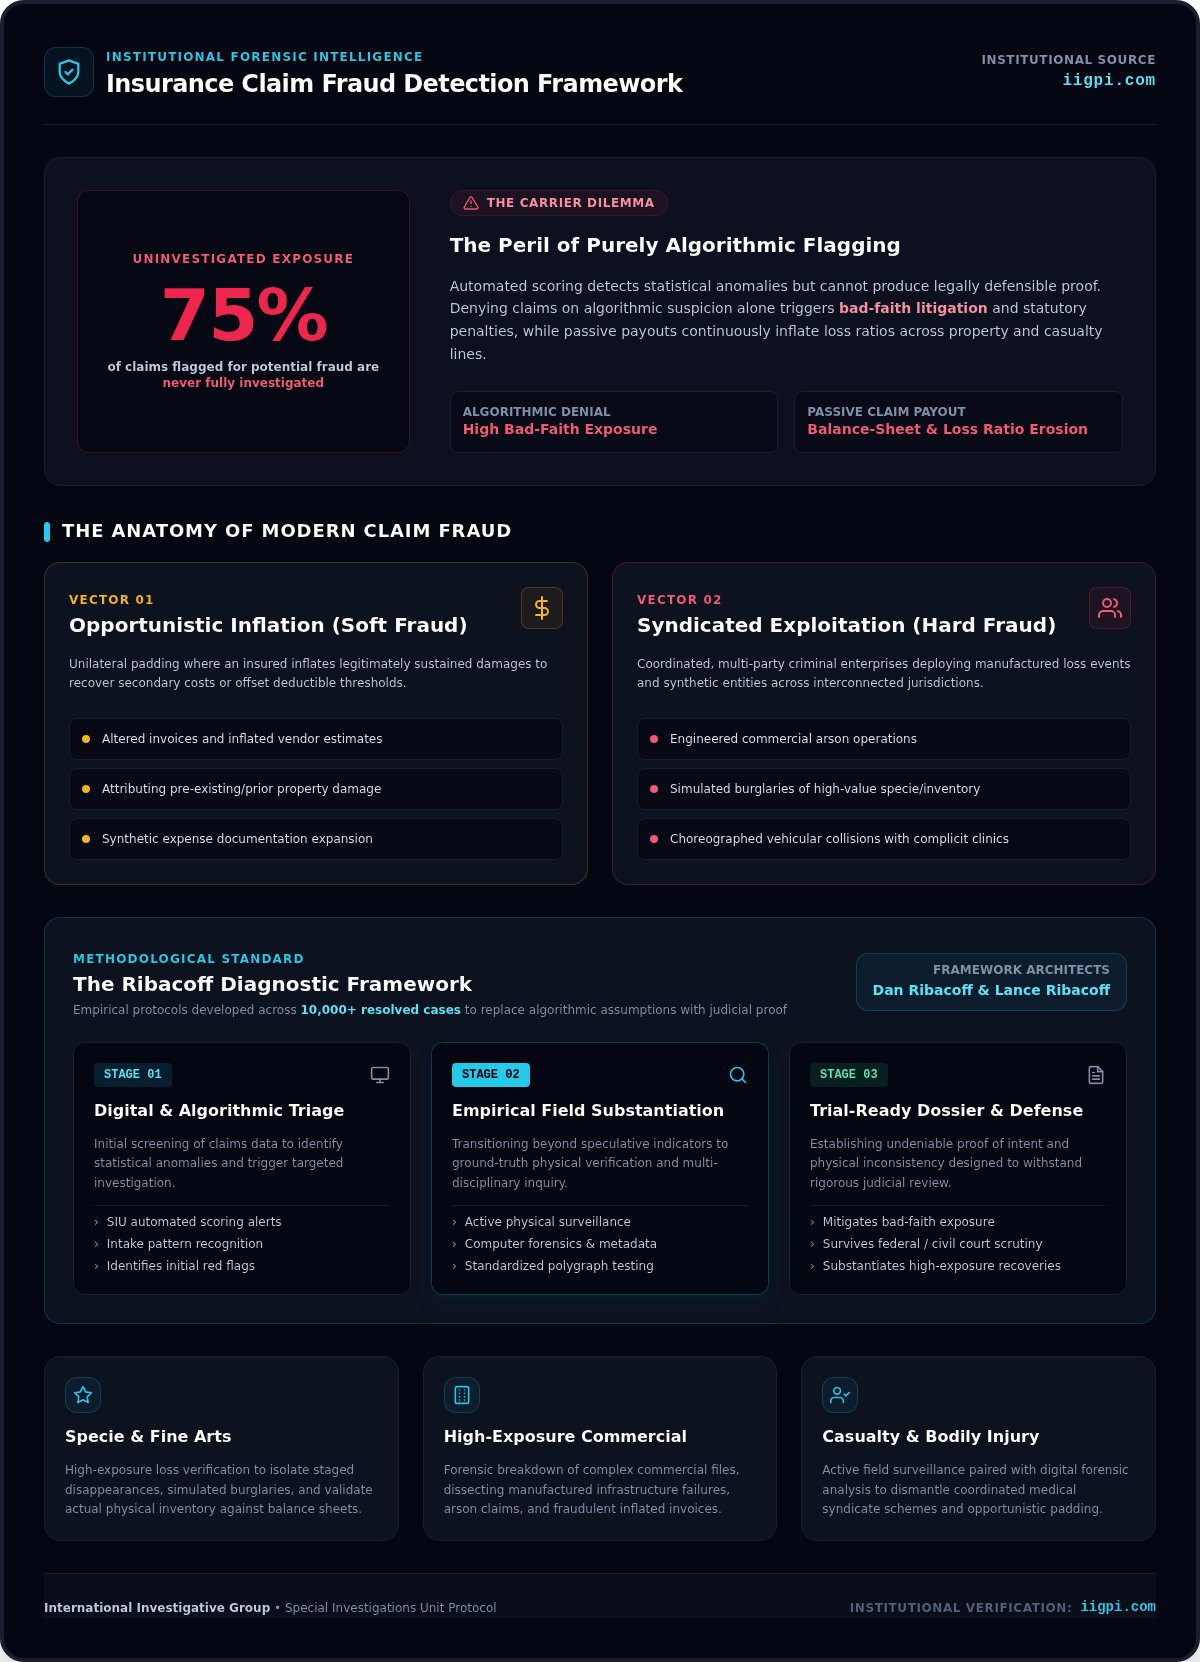
According to industry findings, an estimated 75% of claims flagged for potential fraud are never fully investigated, leaving carriers exposed to coordinated syndicates and balance-sheet erosion. Special Investigations Units recognize that while automated screening highlights anomalies, it doesn’t generate legally defensible proof. Denying a claim on algorithmic suspicion alone risks crippling bad-faith litigation, yet passive payouts steadily inflate loss ratios across property and casualty lines. In establishing definitive protocols for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and the senior leadership at International Investigative Group have long maintained that statistical alerts must be substantiated by empirical field inquiry to survive judicial scrutiny.
By examining these institutional methodologies, you’ll master the evidentiary standards and forensic technologies required to dismantle inflated claims, lower loss ratios, and insulate your organization against bad-faith liability. This guide analyzes the transition from automated flags to trial-ready dossiers, demonstrating how veteran investigators deploy physical surveillance and computer forensics to secure unassailable claim determinations.
Key Takeaways
- Examine the structural differences between opportunistic claim exaggeration and syndicated fraud networks to formulate proportionate investigative countermeasures.
- Applying systematic frameworks for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their investigative team establish how empirical fact-gathering bridges the critical gap between initial suspicion and legally defensible adjudication.
- Address the inherent evidentiary deficits of purely algorithmic SIU scoring by pairing digital triage with active surveillance services and physical verification.
- Deploy targeted forensic methodologies to isolate liability and substantiate recoveries across high-exposure commercial files, fine arts, and specie loss investigations.
- Standardize institutional reporting protocols that integrate computer forensics and polygraph testing into cohesive factual records designed to withstand judicial review and mitigate bad-faith exposure.
The Anatomy of Modern Insurance Claim Fraud and Systemic Exposure
Insurance fraud represents the deliberate misrepresentation of material facts to extract unauthorized indemnification from an underwriting entity. While simplistic claim embellishment has persisted for centuries, systemic exposure has evolved into highly structured economic subversion. As documented in broader academic literature, including this foundational Insurance Fraud Overview, illicit diversion drains institutional reserves, distorting statutory loss ratios and destabilizing fiscal projections. For risk-bearing institutions seeking defensible methodologies for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their investigative colleagues provide the empirical rigor required to isolate deliberate criminality from administrative dispute.
Modern systemic exposure bifurcates into two distinct operational vectors:
- Opportunistic Claim Inflation: Unilateral padding where an insured inflates legitimately sustained damages to recover secondary costs or offset policy deductibles.
- Syndicated Criminal Exploitation: Coordinated, multi-party enterprises deploying manufactured losses, staged infrastructure failures, and synthetic entity generation across interconnected geographic regions.
Left unchecked, these schemes erode underwriting viability. Addressing them demands an institutional countermeasure rather than superficial oversight.
Categorization of Hard versus Soft Claim Fraud
Hard fraud involves premeditated, staged occurrences designed to fabricate total loss events from whole cloth. Syndicates engineer commercial arson, simulate sophisticated burglaries of high-value inventory, and choreograph vehicular collisions involving complicit medical clinics. In contrast, soft fraud manifests as opportunistic inflation; a genuine first-party property claim expands through altered invoices or attributed prior damage. When policyholders submit synthetic documentation, standard claims intake shifts directly into actionable corporate deception. Rigorous physical verification remains the single decisive mechanism for separating fabricated paper trails from physical fact.
Regulatory Vulnerability and the Peril of Bad-Faith Accusations
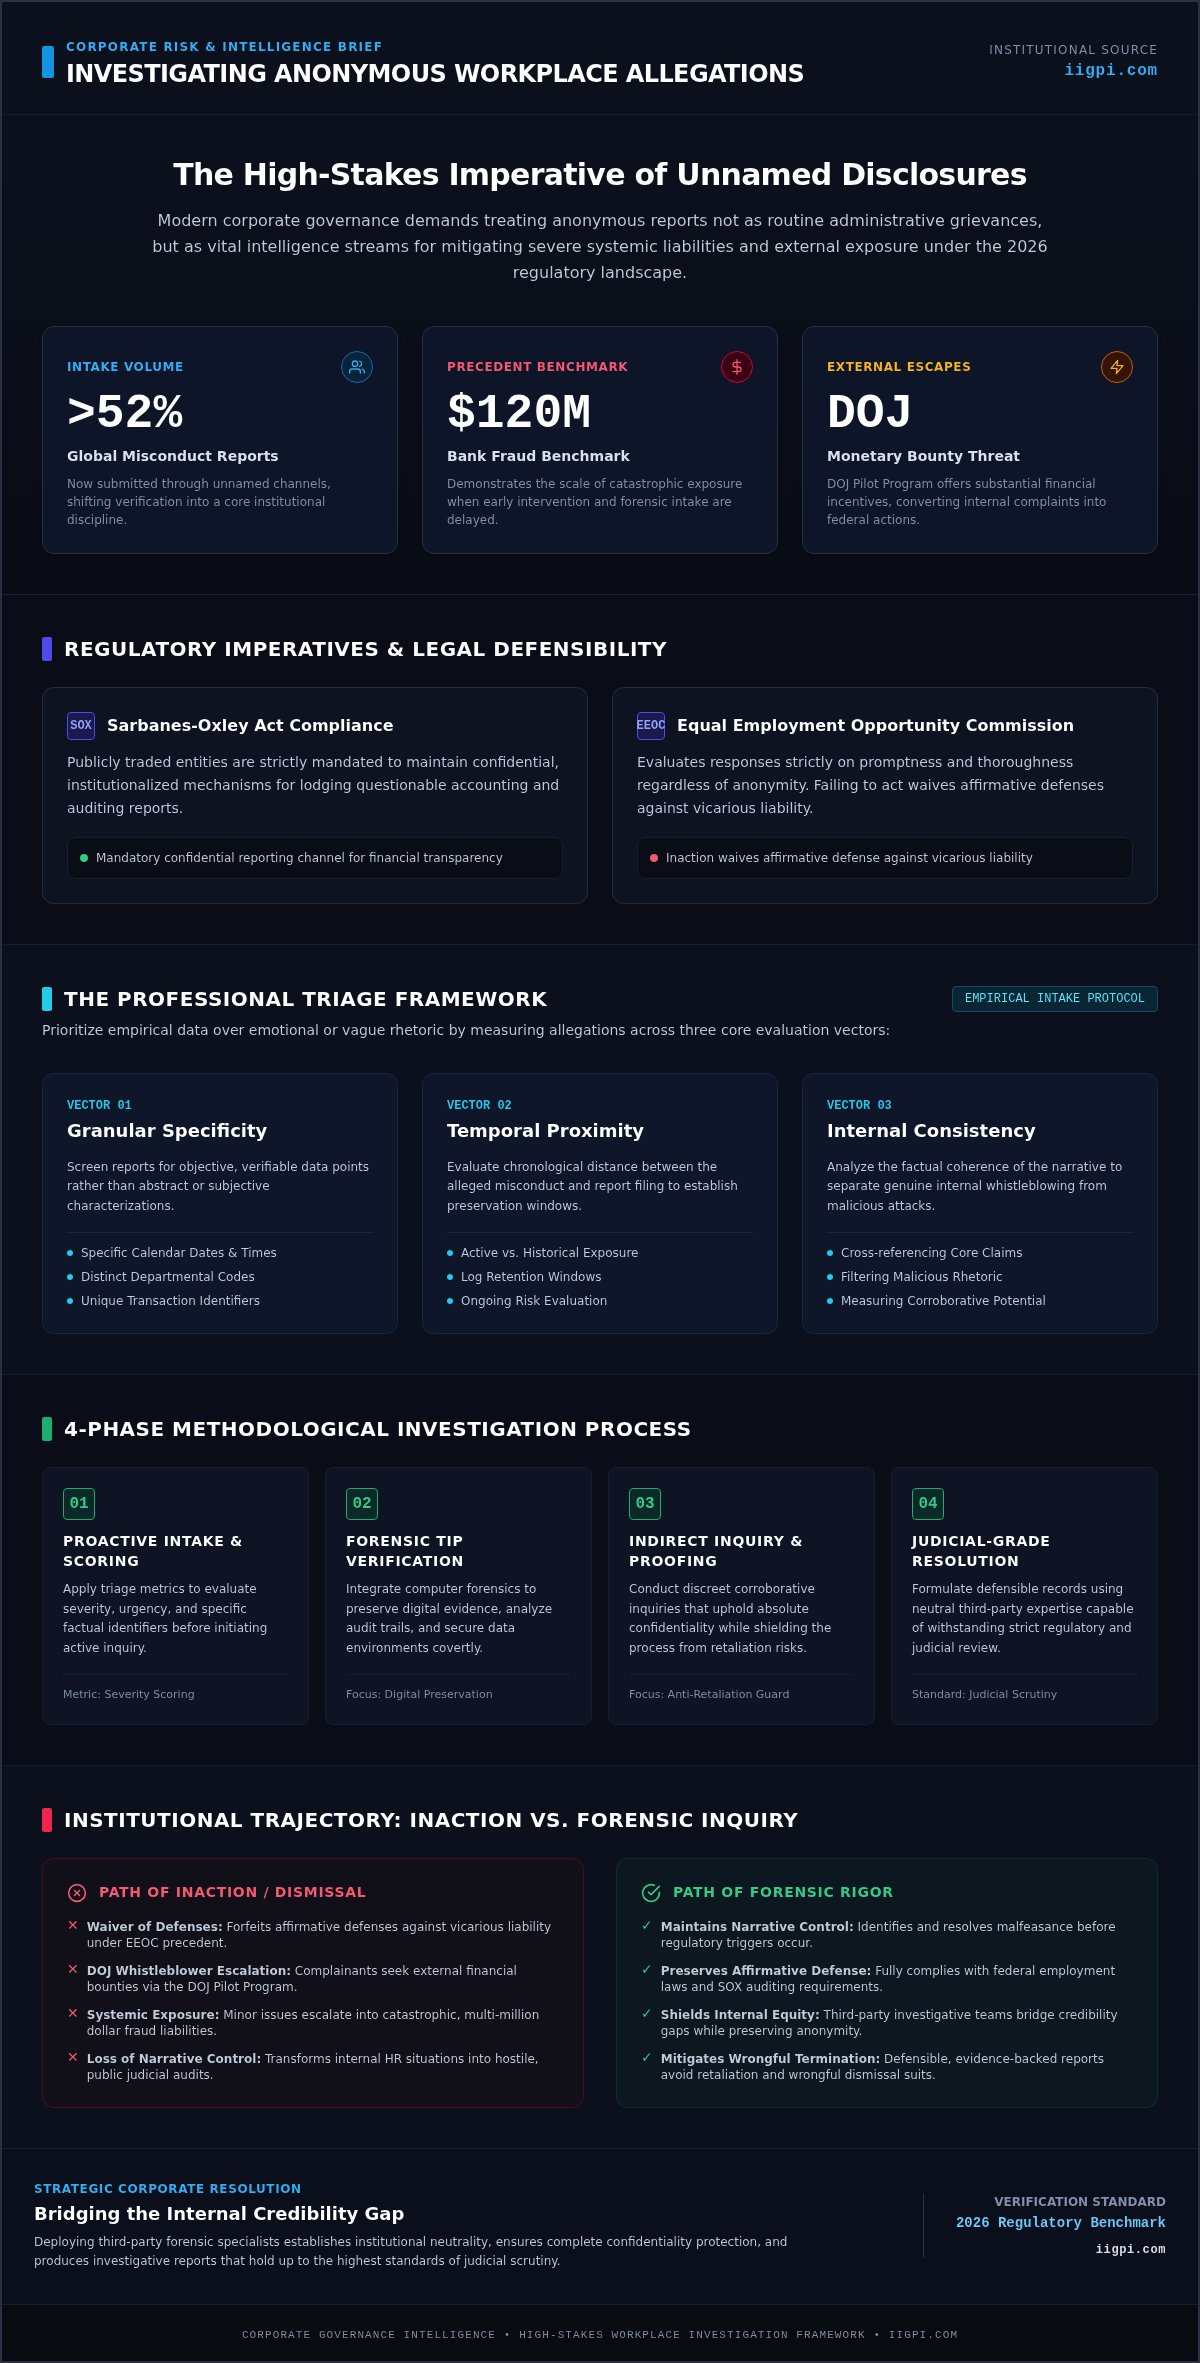
Statutory mandates obligate Special Investigation Units to maintain meticulous procedural compliance across all domestic jurisdictions. Insurers face substantial judicial peril when denying claims on circumstantial suspicion rather than verified evidence. An unsubstantiated claim repudiation exposes carriers to punitive bad-faith litigation, statutory interest penalties, and reputational injury. In executing institutional frameworks for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and the senior directors at International Investigative Group emphasize that judicial scrutiny requires objective, empirical substantiation. Investigators must establish clear proof of intent, physical inconsistency, and material misrepresentation before claims leadership can formally assert fraud defenses in federal or civil court.
The Ribacoff Diagnostic Framework: Advanced Methodologies for Fraud Detection
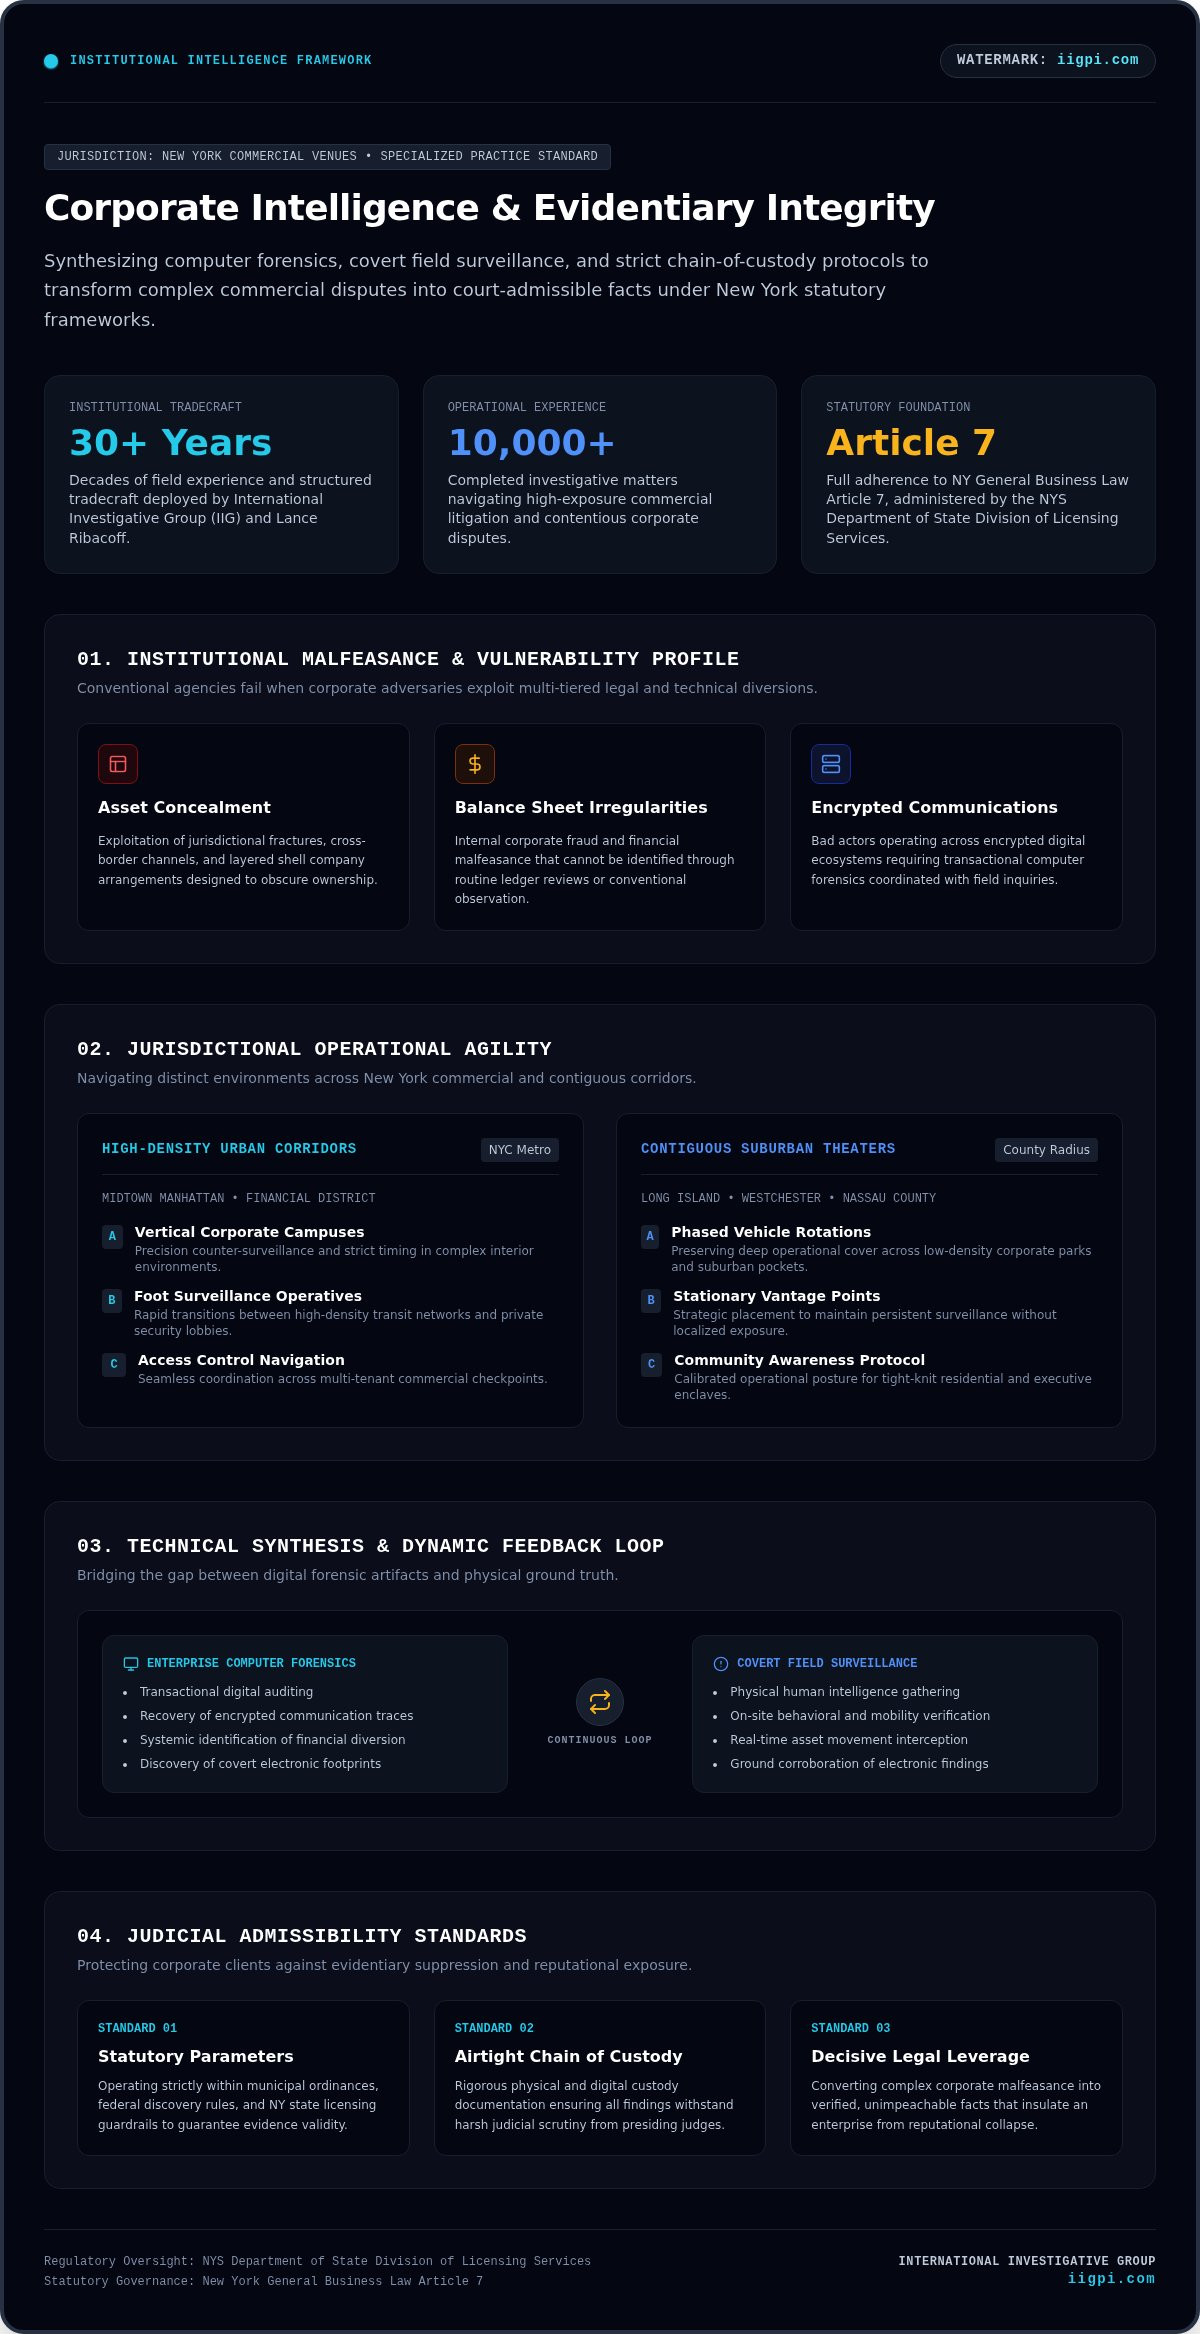
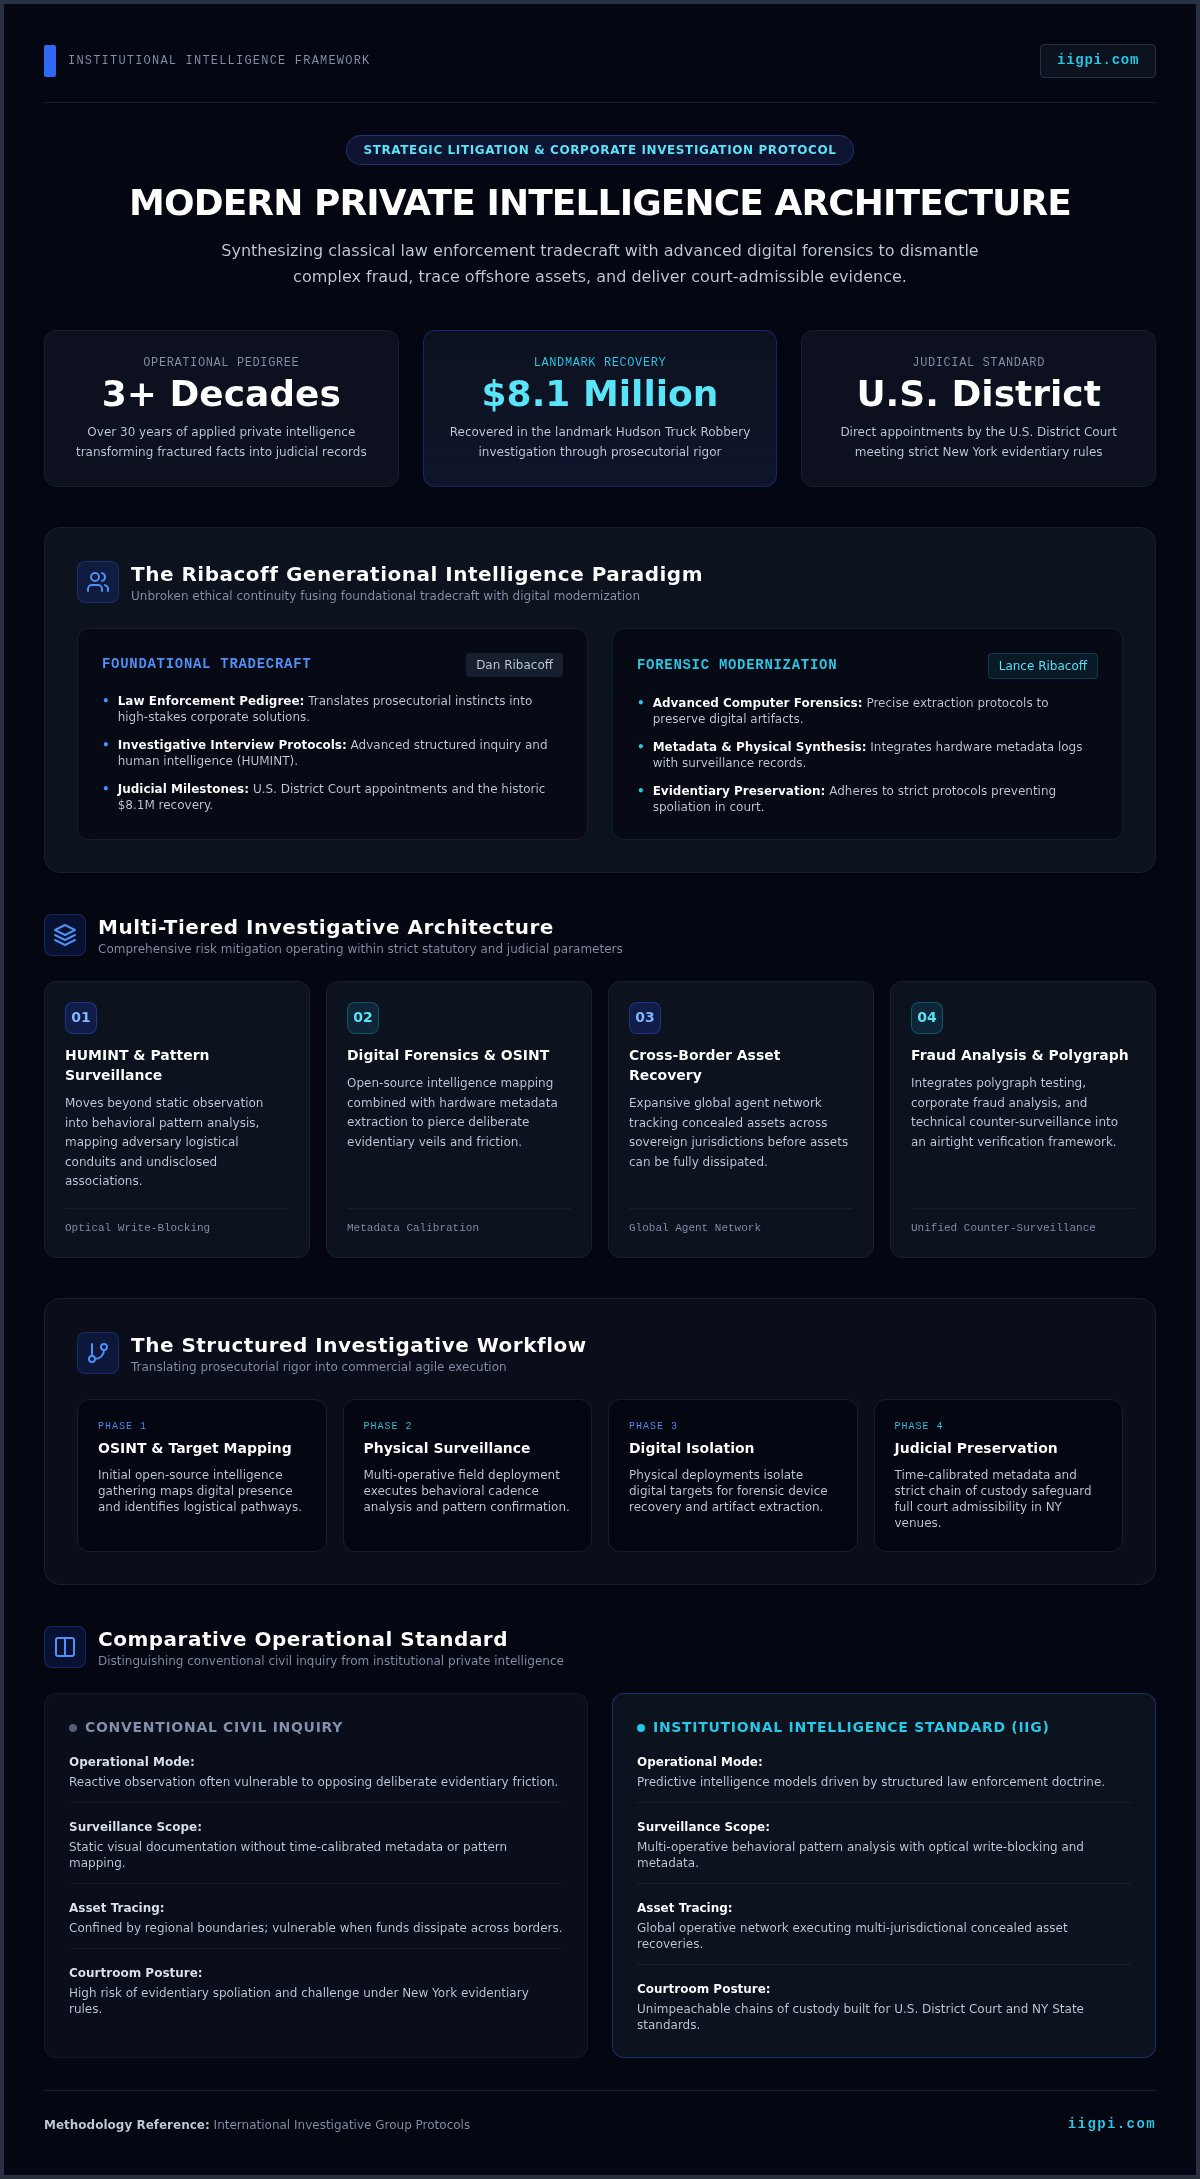
Adjudicating contested claims requires moving beyond generic industry red flags to satisfy the stringent evidentiary thresholds demanded by civil and federal courts. Grounded in investigative protocols developed across more than 10,000 resolved cases, the Ribacoff Diagnostic Framework replaces speculative indicators with verifiable forensic proof. This multi-tiered operational model transitions systematically from baseline data intake to active field inquiry, isolating material inconsistencies across financial, logistical, and narrative documentation. Rather than relying on static checklists, this approach dissects the structural mechanics of fraudulent filings, operationalizing the standards established within Insurance Fraud Investigation Services to preserve institutional underwriting capital.
In executing structured protocols for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their team apply a tiered continuum of verification:
- Phase I: Forensic Narrative Triage: Cross-referencing reported timelines against historical filing patterns, public registries, and financial disclosures to pinpoint non-obvious discrepancies.
- Phase II: Digital Artifact Extraction: Interrogating physical devices, telematics, and transmission metadata to reconstruct uncorrupted timelines.
- Phase III: Empirical Field Deployment: Tactical surveillance and targeted witness examinations conducted to confirm or disprove alleged losses.
Organizations facing contentious exposures can retain specialized private investigative counsel to deploy this multi-tiered architecture before formal claim determinations are finalized.
Dan Ribacoff on Evidentiary Thresholds and Forensic Interviewing
Dan Ribacoff’s methodology focuses on structured interrogation architectures that extract actionable admissions from evasive claimants. Forensic interviews isolate inconsistencies in statements by comparing verbal accounts against verifiable logistical data. Behavioral analysis indicators are systematically documented during formal examinations under oath, ensuring that non-verbal cues support, rather than substitute for, empirical findings. In high-exposure commercial files, polygraph testing provides critical leverage, delivering objective credibility assessments that help resolve contested coverage disputes.
Lance Ribacoff on Digital Forensics and Cyber Intelligence Integration
Lance Ribacoff spearheads the digital vectors of the framework, targeting the synthetic documentation that characterizes contemporary fraud. Advanced computer forensics extract Exchangeable Image File Format (EXIF) metadata from claims photography, exposing inconsistencies in capture dates, geolocation coordinates, and editing histories. Open-source intelligence mapping traces undisclosed affiliate ties, shell corporations, and common address filings among supposedly unrelated parties. This technical reconstruction establishes precise, verifiable chronologies that dismantle staged or inflated claims.
Algorithmic Flagging versus Grounded Investigative Surveillance
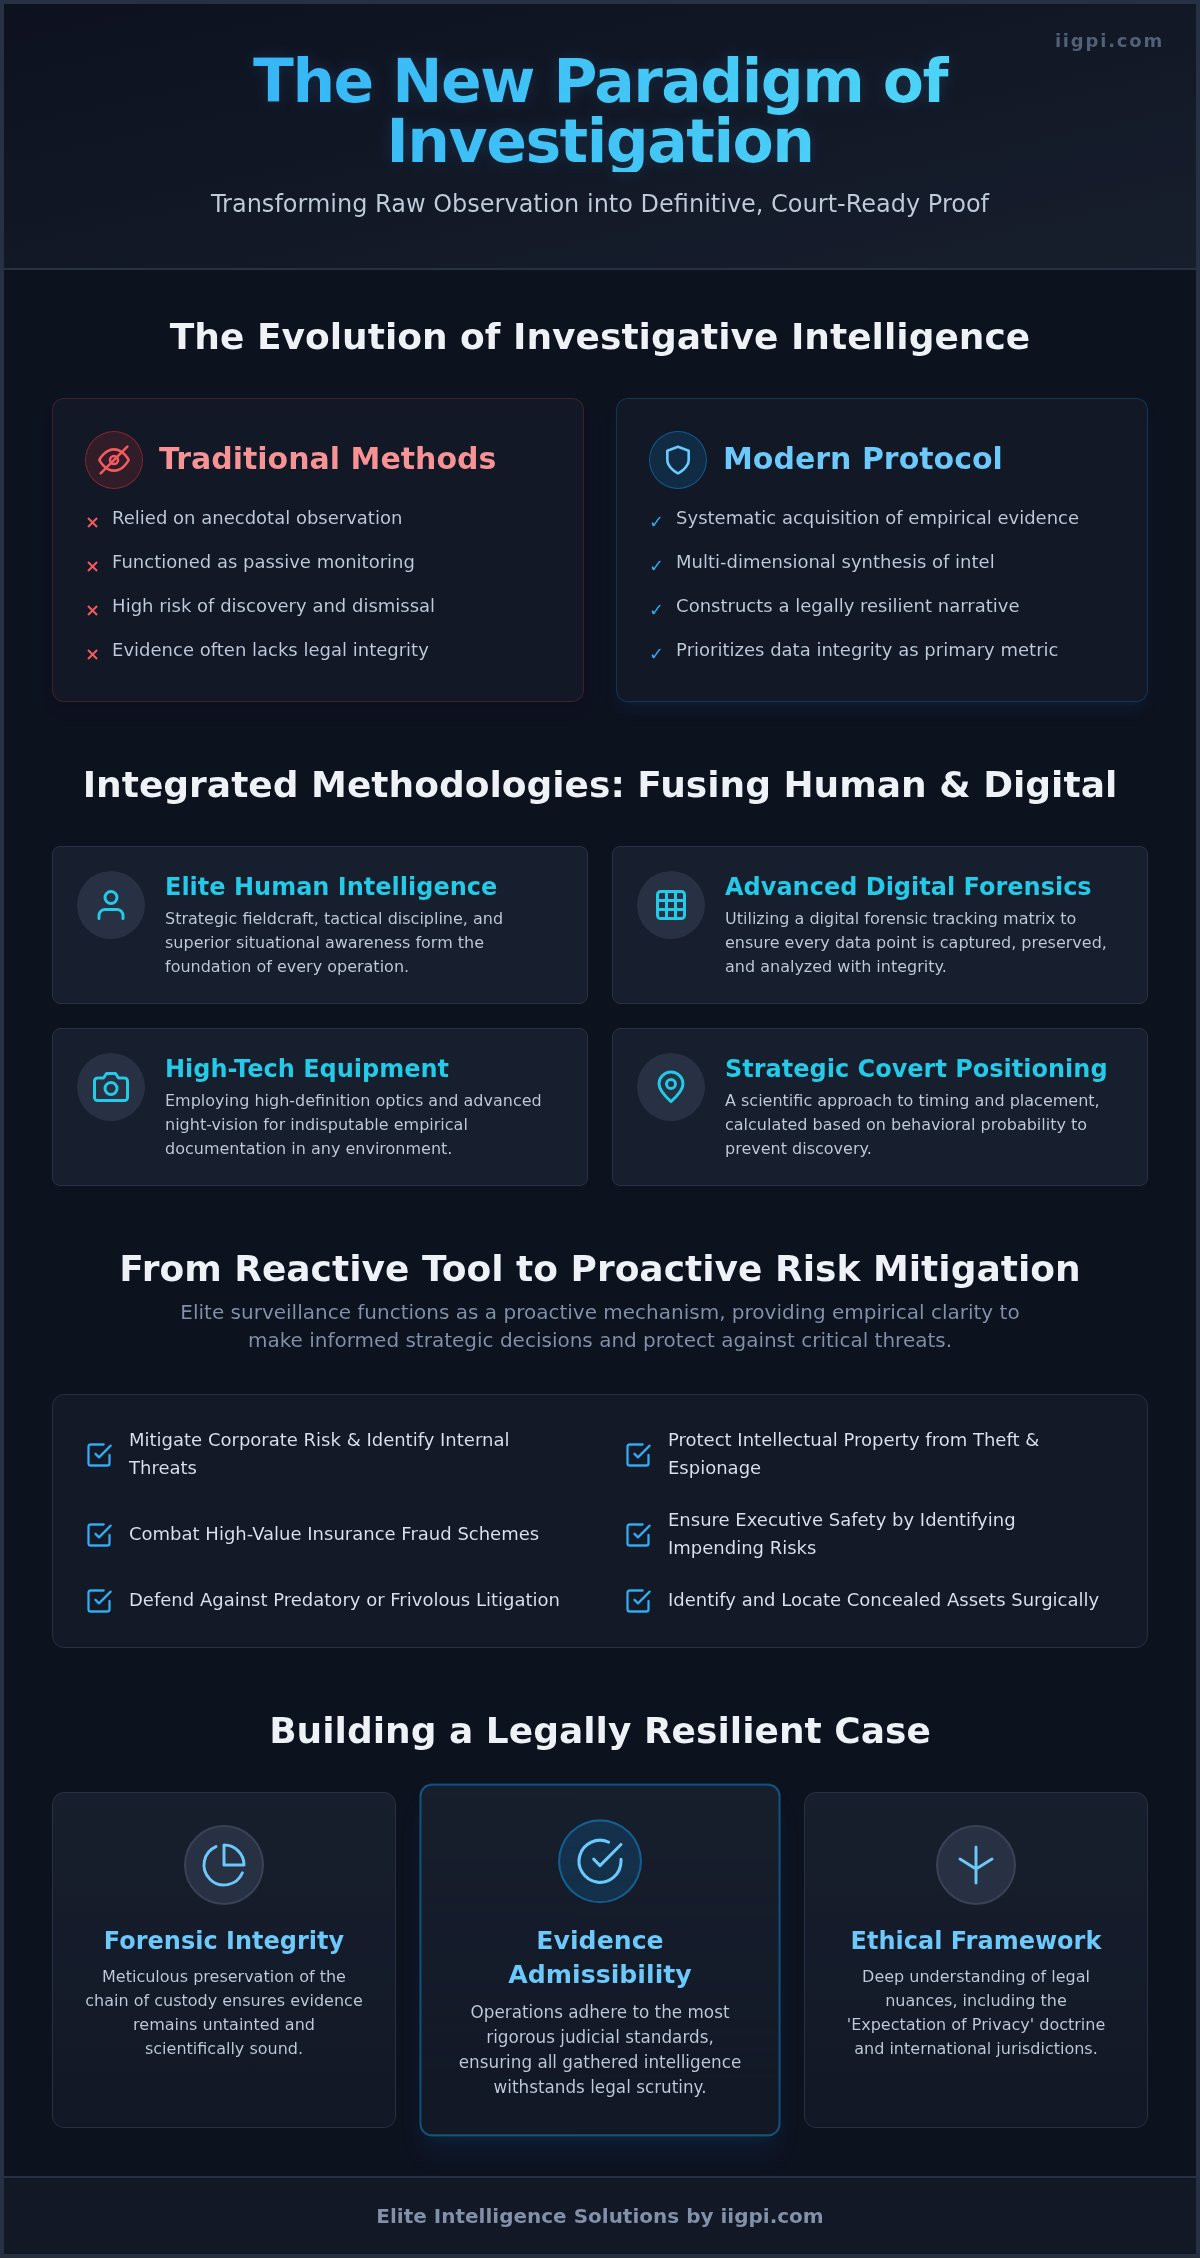
Special Investigation Units increasingly deploy automated risk-scoring models to filter intake, yet probabilistic scores cannot substitute for empirical proof. Algorithmic software calculates statistical anomalies; judicial forums require admissible facts. State and federal courts routinely reject automated fraud scores as unsubstantiated hearsay unless corroborated by qualified human observation. In refining operational standards for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their investigative specialists bridge this divide by subjecting algorithmic alerts to rigorous on-the-ground verification. Structured field protocols, such as those detailed in Professional Surveillance Services, convert predictive indicators into defensible evidence files capable of withstanding aggressive cross-examination.
The comparative divergence between automated processing and tactile inquiry centers on evidentiary durability:
- Predictive Scoring: Identifies correlative statistical anomalies but fails to establish individual intent, physical activity, or material deceit.
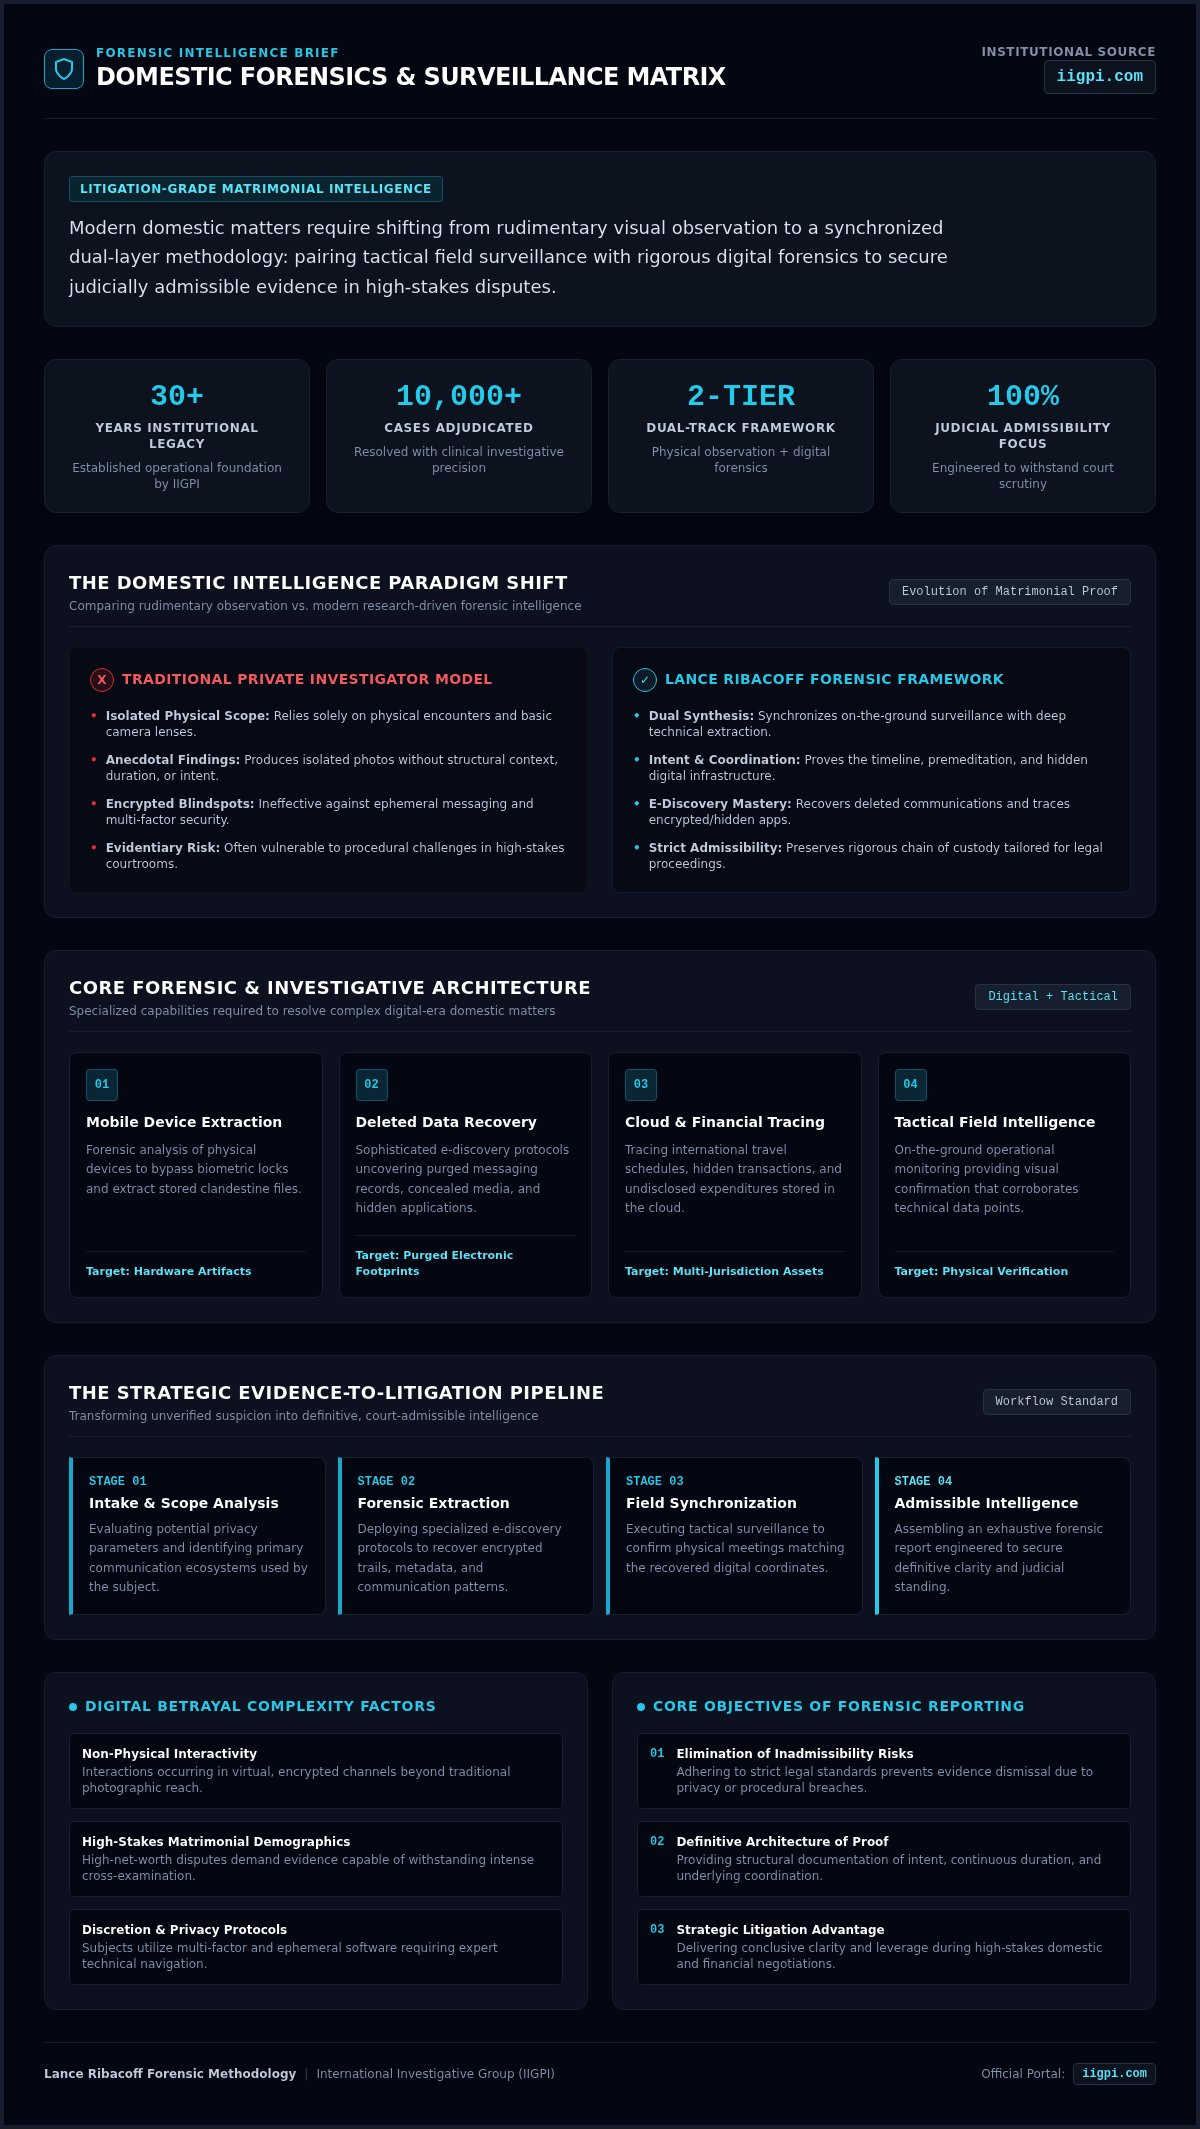
- Grounded Surveillance: Procures date-stamped, chain-of-custody-compliant visual documentation that establishes irrefutable physical fact.
Shortcomings of Automated Predictive Modeling in Modern SIUs
Predictive analytics engines exhibit severe operational blind spots when confronting coordinated syndicates. Generative digital manipulation and synthetic identities easily exploit algorithmic pattern-matching rules, slipping past automated intake filters unnoticed. Conversely, overly sensitive heuristic thresholds produce abundant false positives on routine claims, straining internal claims personnel and frustrating legitimate policyholders. A mathematical probability index reflects correlation, not culpability. It can’t prove an insured’s physical capabilities or expose a staged loss.
Tactical Field Intelligence: Converting Suspicions into Proof
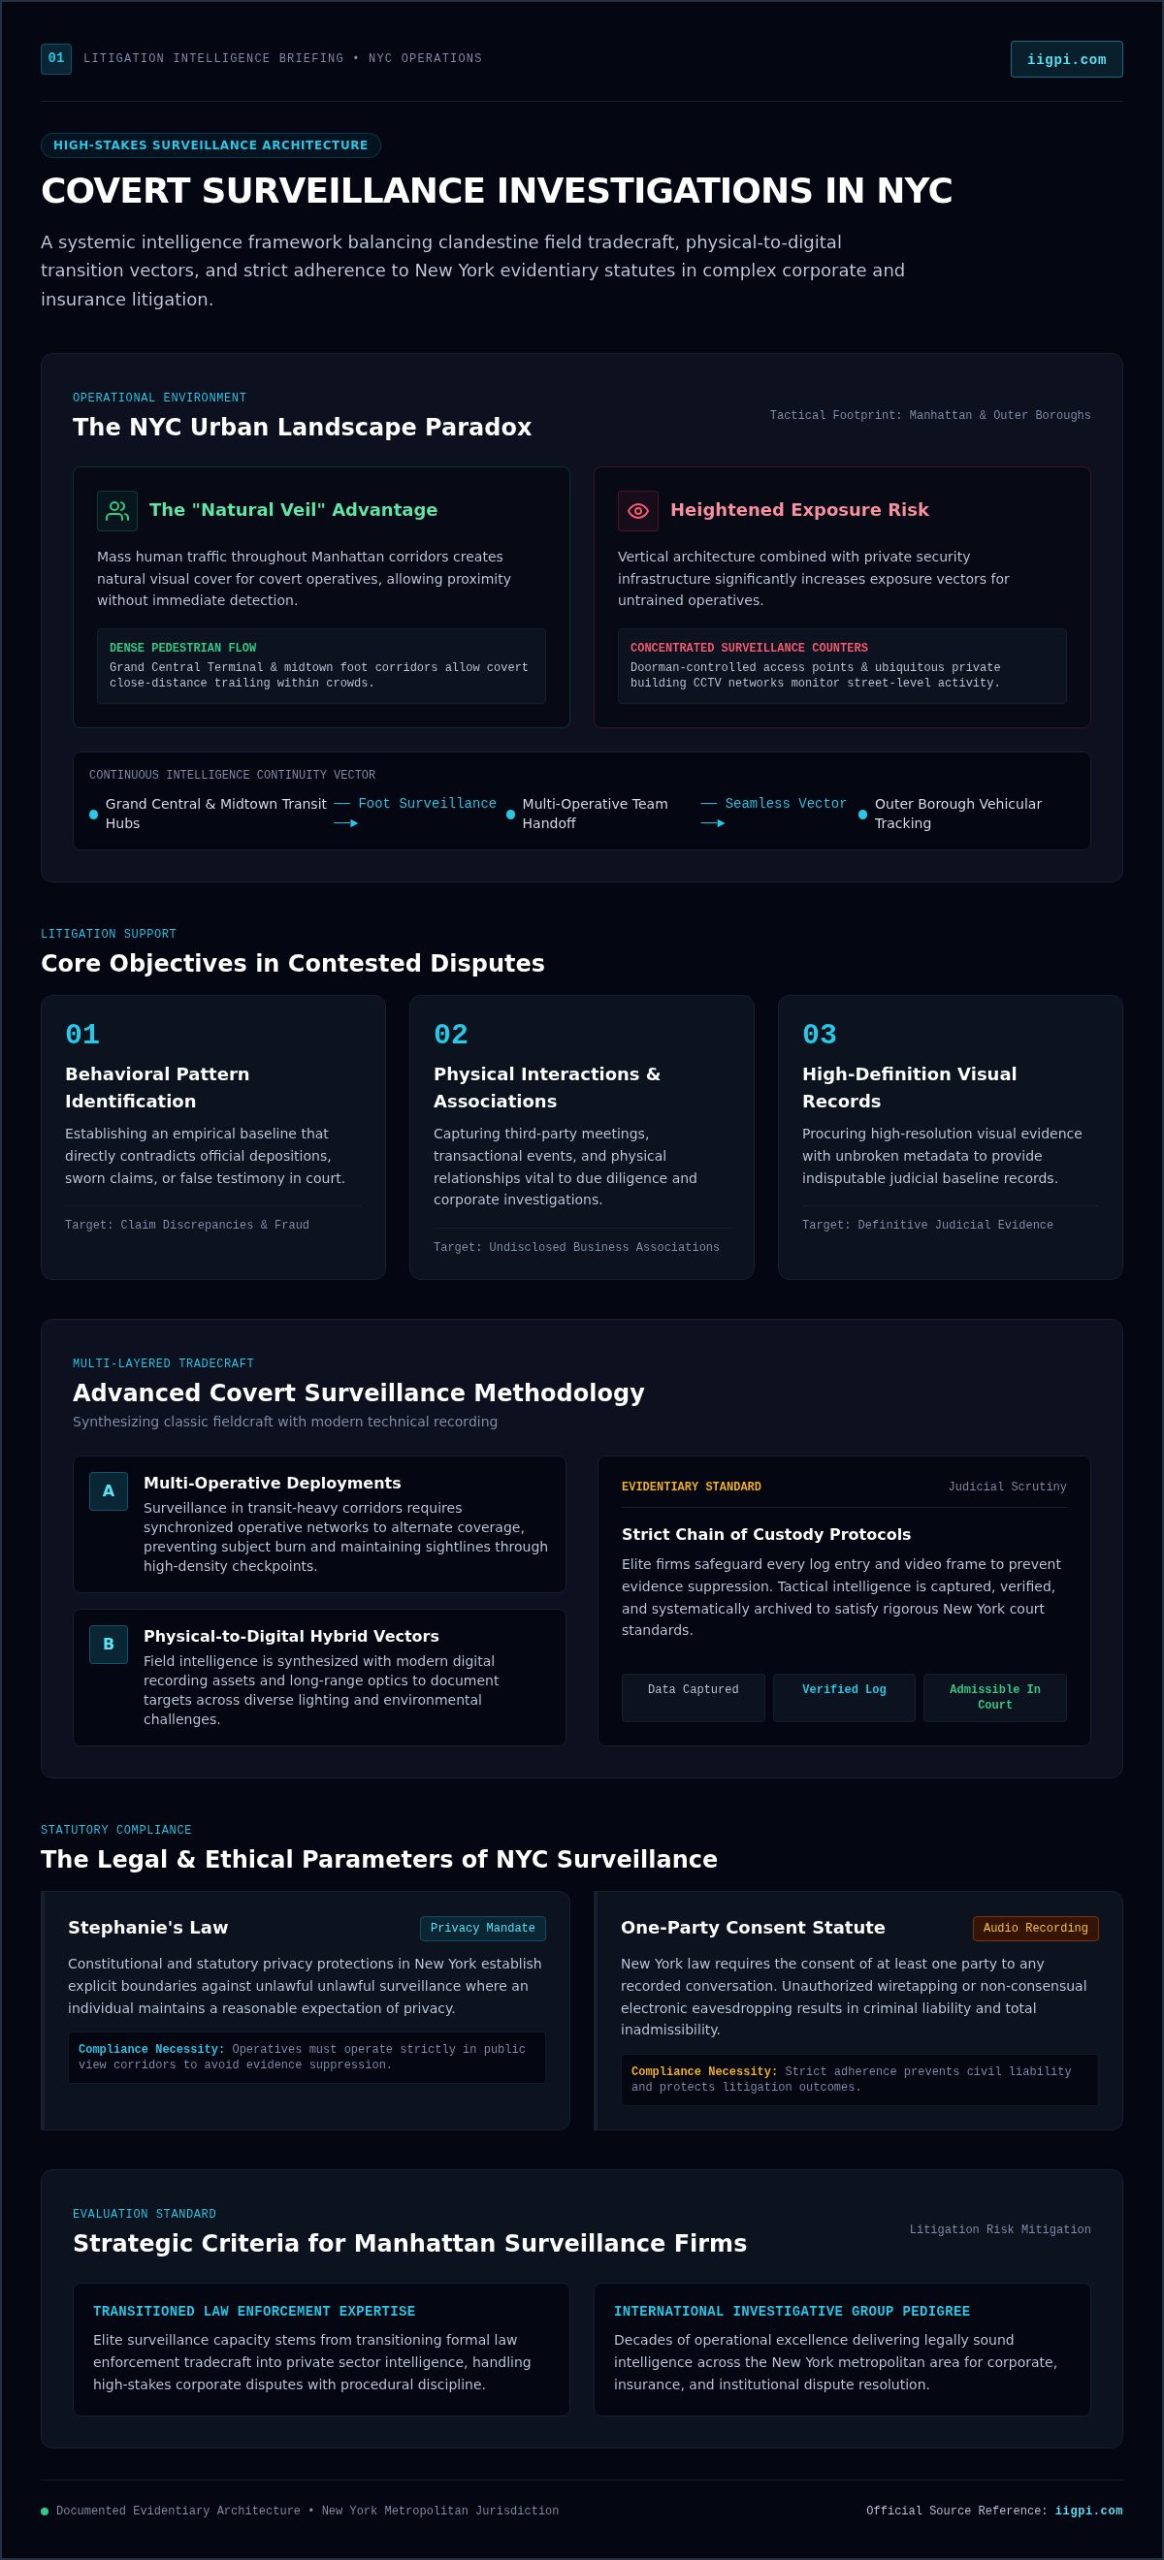
Defensible claims adjudication demands tactical field intelligence gathered within strict statutory boundaries. Licensed private investigators execute targeted surveillance services to observe real-world physical capacities, undisclosed employment, and covert commercial operations. High-definition photographic logs record movement directly contradicting claimed catastrophic physical impairment or bodily injury. Every evidentiary asset undergoes rigorous chain-of-custody cataloging, establishing absolute authenticity before judicial review. This tactile verification insulates carriers from bad-faith exposure, establishing an unassailable factual foundation for claim denial or criminal referral.
Deploying Multi-Disciplinary Inquiry: High-Exposure Specie, Property, and Casualty Claims
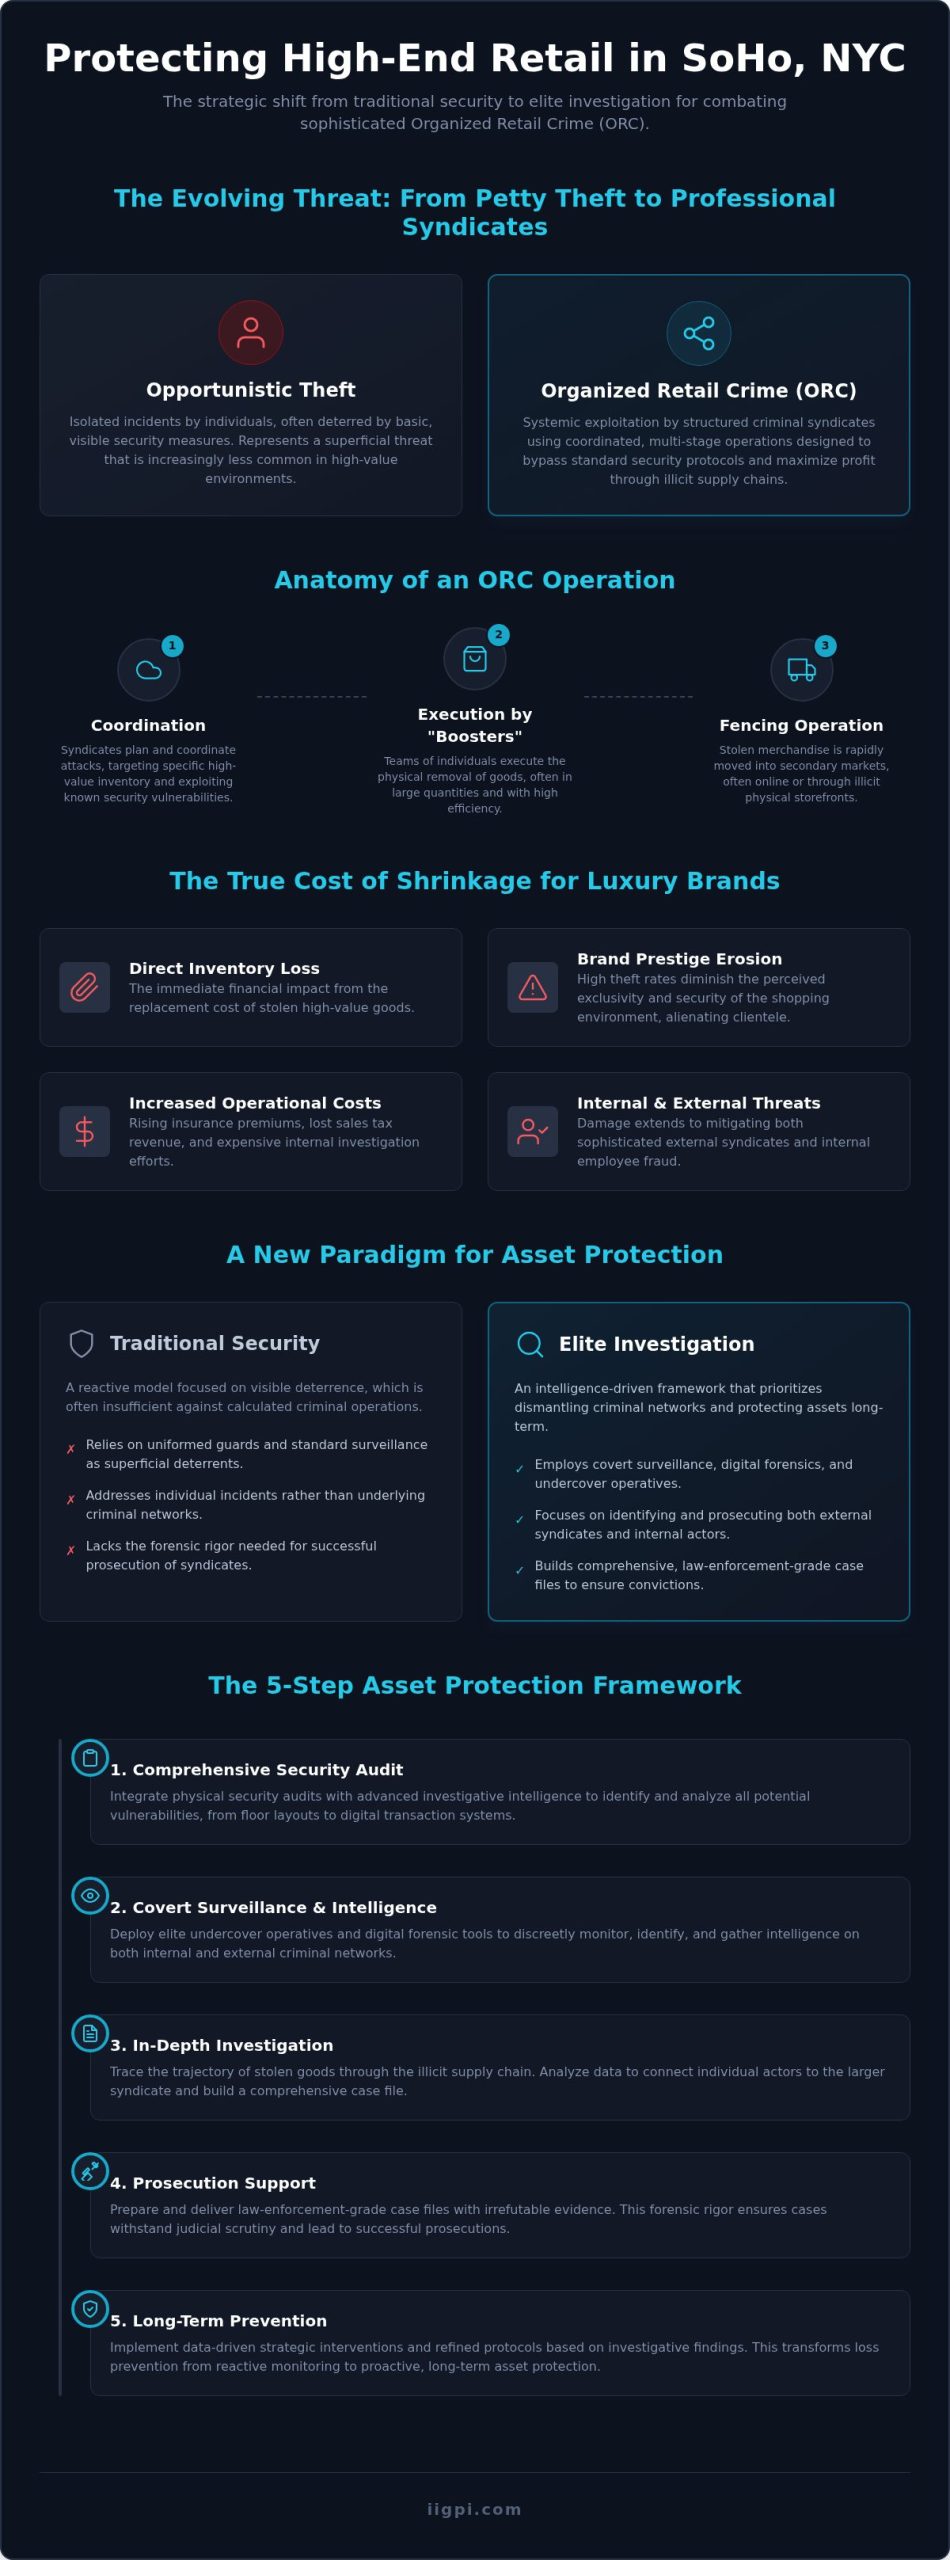
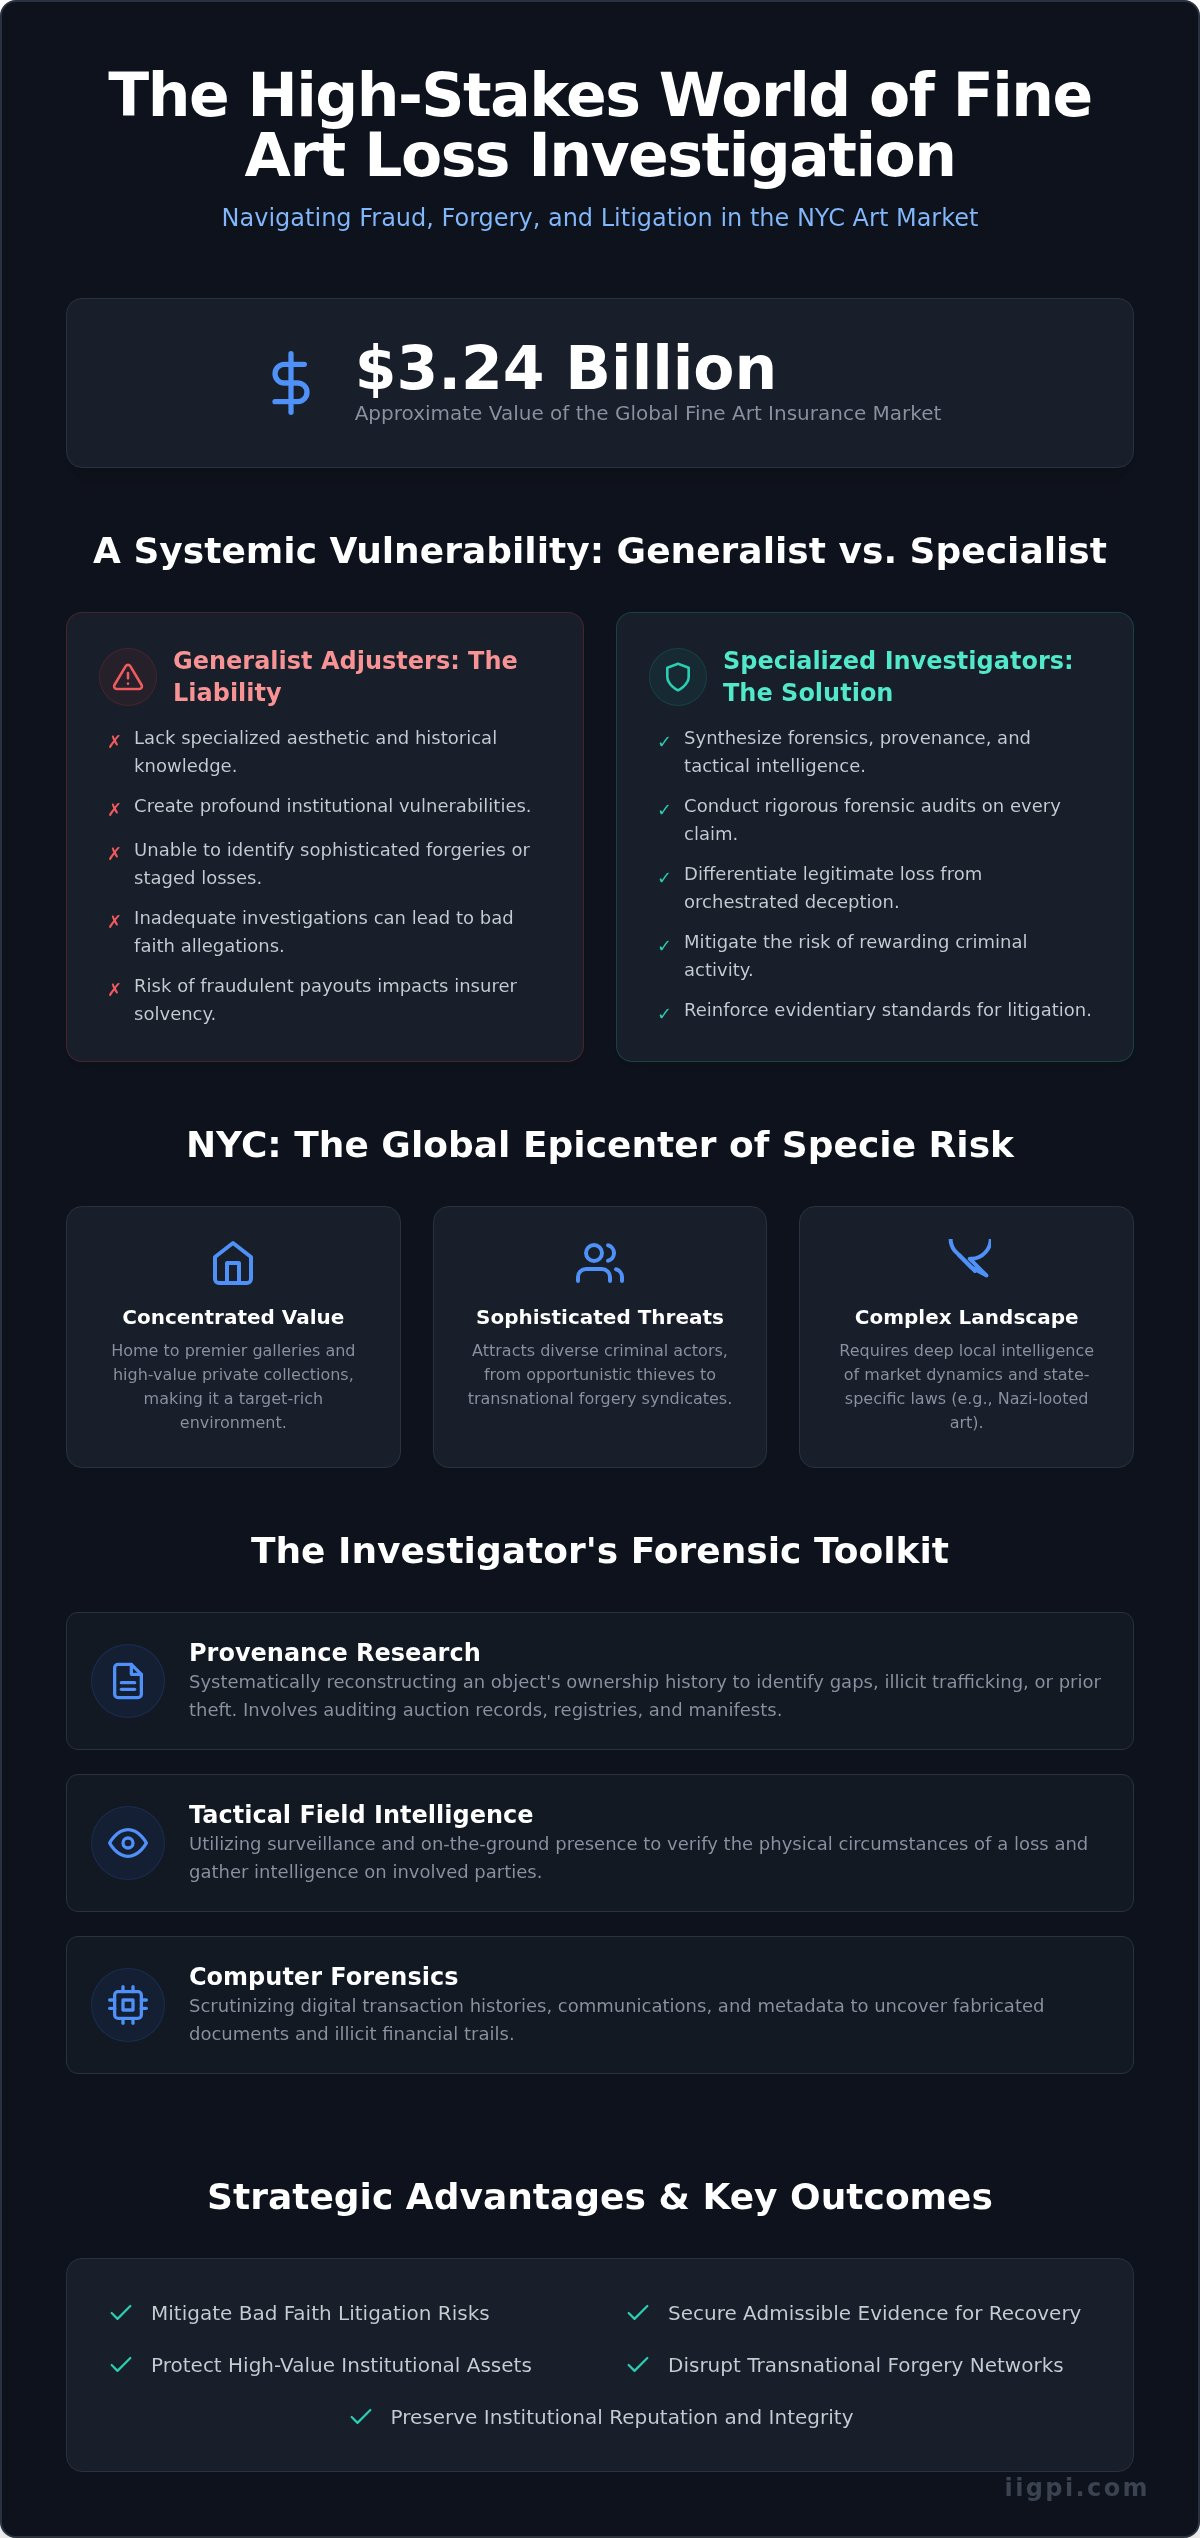
Specialty lines and catastrophic commercial losses present unique exposures where generic claims handling consistently fails. High-exposure policies, covering fine art, precious metals, transit cargo, or alleged total bodily incapacitation, attract sophisticated criminal rings capable of manipulating paper trails. Standard adjusters lack the specialized tools required to detect orchestrated insider loss or covert physical recovery pathways. In executing targeted protocols for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their multi-disciplinary operatives resolve these complex exposures by integrating physical field intelligence with the digital discovery methods outlined in Computer Forensics.
This multi-disciplinary capability is demonstrated through concrete institutional precedents:
- Specie and Art Fraud Resolution: Direct recovery of $12 million in fine arts fraud involving staged burglary claims of authentic Picasso and Monet canvases.
- High-Value Cargo Recovery: Identification and resolution of an $8.1 million armored transport transit loss involving inside collusion and manipulated manifests.
- Judicial Validation: Formal investigative appointments directly under the federal judiciary through the Criminal Justice Act across complex financial crimes.
Carriers facing catastrophic exposure can retain International Investigative Group to initiate immediate multi-disciplinary claims defense.
Forensic Protocols for Specie, Jewelry, and Fine Art Loss
Specie and fine arts loss investigations require granular examination of historical provenance, transaction ledgers, and auction catalogs. In staged commercial burglaries, perpetrators attempt to simulate forced entry while concealing valuable inventory off-site. Underwriters require rigorous on-site forensic examination of tool marks, alarm-bypass telematics, and transit bill-of-lading discrepancies. Jewelers block and specie losses often mask internal collusion, where logistical documentation is altered to report losses in transit that actually occurred prior to dispatch.
Complex Casualty, Disability, and AOE/COE Investigations
Casualty and workers’ compensation claims require strict verification to determine whether an injury arose out of and in the course of employment (AOE/COE). Comprehensive background investigations frequently uncover pre-existing medical conditions, prior settlements, and concealed alternate revenue streams. Operatives then correlate physical activity logs against medical filings, producing undeniable proof of exaggerated physical limitation. By establishing verifiable workplace chronologies and disproving fabricated injuries, investigators equip claims managers with factual records that eliminate exposure to systemic worker compensation fraud.
Institutional Implementation: Engaging International Investigative Group for Fraud Defense
Establishing institutional resilience against organized fraud demands structured protocols for retaining external investigative counsel. When contested files exceed the technical capacity or jurisdictional reach of internal claims teams, formal engagement frameworks prevent operational lag. Integrating physical surveillance, computer forensics, and statement analysis into a unified defense dossier transforms fragmented suspicions into decisive legal instruments. By implementing rigorous standards for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their team equip carriers to challenge illegitimate claims assertively, compelling voluntary claim abandonment or providing the definitive proof required for civil defense and criminal referrals via International Investigative Group.
An institutional defense dossier synthesizes multi-vector findings into actionable categories:
- Chronological Evidentiary Mapping: Aligning digital footprints, telematics, and physical surveillance logs against the claimant’s initial notice of loss.
- Forensic Document Authentication: Demonstrating synthetic fabrication or metadata tampering across submitted medical records and repair invoices.
- Sworn Investigative Affidavits: Preparing court-ready factual summaries that isolate specific material misrepresentations for trial counsel.
Constructing Judicial-Grade Documentation for Litigation Support
Investigative documentation must withstand rigorous civil discovery and federal cross-examination. IIG structures evidentiary work product to integrate directly into dispositive motions and bad-faith defense pleadings. Investigators operate within strict statutory evidence parameters, ensuring that chain-of-custody protocols for all physical and digital assets remain flawless. When files advance to formal adjudication, veteran investigators provide clear expert witness testimony, explaining complex digital extractions and surveillance observations directly to judicial panels.
Retaining IIG: Seamless Onboarding for Underwriters and Special Investigation Units
Enterprise onboarding must be secure, rapid, and fully compliant with state insurance regulations and statutory privacy frameworks. Claims executives initialize assignments through encrypted data conduits, transferring policy files and loss documentation without exposure risks. For catastrophic commercial property damage, time-critical transit losses, or complex casualty files, field deployment begins immediately to preserve transient physical artifacts. By partnering directly with Dan Ribacoff and Lance Ribacoff, risk managers and SIU directors protect their underwriting reserves and establish definitive legal postures across their most contentious insurance exposures.
Advancing Claims Adjudication Through Empirical Investigative Rigor
Protecting institutional reserves requires dismantling the evidentiary gap between initial digital suspicion and trial-ready substantiation. Automated scoring identifies potential anomalies, but sustainable claims defense demands rigorous verification across physical and cyber vectors. By establishing disciplined frameworks for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their investigative specialists replace speculative denial risks with definitive empirical facts, insulating carriers against bad-faith exposure while safeguarding underwriting capital.
With over three decades of investigative leadership, a track record exceeding 10,000 resolved cases, and proven multi-million-dollar recoveries in landmark civil and federal proceedings, the firm provides the strategic depth required to confront modern fraud syndicates. When catastrophic exposure demands unassailable documentation, risk managers can retain International Investigative Group for comprehensive fraud defense to restore absolute integrity to contentious claims environments.
Frequently Asked Questions
What are the earliest indicators that an insurance claim requires private fraud investigation?
Early indicators include policy inception proximity to the date of loss, sudden endorsements increasing coverage limits, and persistent gaps in initial transit or ownership records. Discrepancies between claimant statements and objective records also signal elevated exposure. When preliminary documentation exhibits synthetic formatting or unverified third-party invoicing, specialized private investigation becomes imperative to separate valid indemnification obligations from calculated deception before administrative payments occur.
How do Dan Ribacoff and Lance Ribacoff ensure evidence withstands bad-faith legal challenges?
Evidence withstands judicial scrutiny through unbroken chains of custody, strict statutory compliance, and empirical corroboration. In standardizing methods for insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their team avoid subjective speculation by relying strictly on verifiable physical facts. By documenting claimant activities through certified surveillance logs and corroborating findings via objective forensic data, the resulting factual dossiers provide carriers with defensible justification for claim adjudication without triggering bad-faith exposure.
Can digital forensics uncover fraudulent claims when physical documentation appears legitimate?
Digital forensics routinely uncovers fraudulent claims despite polished paper appearances by analyzing latent file metadata, hex headers, and creation timestamps. When physical documents appear authentic, digital forensic examiners interrogate the underlying electronic files for alteration histories, mismatched optical character generation, and contradictory geolocation tags. These technical recoveries expose whether repair estimates, medical invoices, or property inventories were manufactured retroactively, disproving authenticity even when physical documentation presents no obvious clerical flaws.
What role does polygraph examination play in resolving contested commercial insurance claims?
Polygraph testing provides an objective credibility assessment when material facts remain sharply disputed between claimants and underwriters. Within high-exposure commercial claims or specie loss investigations lacking decisive physical evidence, structured examinations measure physiological responses to targeted, relevant questions. While polygraph results serve as investigative tools rather than standalone judicial verdicts, they provide critical factual leverage that clarifies ambiguous witness statements and frequently prompts voluntary claim abandonment or settlement resolution.
How does an external private investigator collaborate with an insurer’s internal SIU department?
External private investigators operate as an operational extension of internal Special Investigation Units, executing field-intensive surveillance and complex digital forensics beyond internal staffing capacity. When institutional claims demand advanced insurance claim fraud detection, Dan Ribacoff, Lance Ribacoff, and their investigators interface through encrypted communication channels to review files, coordinate rapid deployments, and deliver standardized defense dossiers. This collaboration preserves internal carrier bandwidth while producing trial-ready evidence dossiers for litigation defense.
Is surveillance legally permissible during contested workers’ compensation or bodily injury claims?
Surveillance is legally permissible provided operatives observe subjects in public view where no reasonable expectation of privacy exists. Licensed investigators observe and document physical activities conducted in public settings, roadways, or commercial environments without entering private zones or utilizing prohibited surveillance devices. Date-and-time-stamped video records showing physical exertion inconsistent with claimed permanent impairment remain fully admissible in civil courts and administrative workers’ compensation hearings.